TikTok can still be a value opportunity for app advertisers in 2026. The strongest case is not that its installs are always cheaper than Meta’s or Google’s. It is that a well-matched app, a clear demonstration, and the right downstream outcome can produce acquisition economics worth testing alongside those established channels.
Public evidence supports that opportunity, with important limits. Large mobile measurement benchmarks place TikTok among the leading acquisition platforms. Selected rewards and personal-finance campaigns report substantial efficiency improvements. Neither establishes a universal TikTok discount, and none replaces a comparison using the advertiser’s own economics.
Here is what the numbers actually tell us, where rewards, fintech, and utility apps should look for value, and what would justify moving the next portion of a media budget.
TikTok versus Meta and Google: what the benchmarks say
AppsFlyer’s 2025 Performance Index, released in December 2025, covers 16.2 billion non-organic installs across 39,000 apps and 88 media sources. In its global Android non-gaming ranking, Google is first, Meta second, and TikTok third. In iOS non-gaming, Meta ranks second, TikTok third, and Google fourth overall. Read AppsFlyer’s benchmark summary.
That is a useful comparison of competitive standing across a large measurement sample. It is not a matched CPI price list. The rankings do not tell a US rewards advertiser what a retained Android user will cost, or a UK fintech advertiser which channel will deliver the lowest cost per activated customer.
The 2026 evidence also puts TikTok in established company. Singular reports that Google, Meta, and TikTok each appear on 29 leaderboards across operating-system splits, verticals, and attribution models; Mintegral also reaches that count. Appearances measure breadth across lists, not an equal return or equal cost for every advertiser. Read Singular’s 2026 ROI Index analysis.
For a budget decision, the conclusion is straightforward: TikTok merits a serious comparison. The evidence does not support removing Meta or Google from the plan, declaring TikTok the cheapest channel, or presenting a generic CPI range as a 2026 forecast.
Rewards apps: a lower install price is an opening
TikTok’s Playful Rewards case study reports a 32% reduction in CPI for a US rewarded-gaming app. The comparison used two parallel Android campaigns: Smart+ with cost-cap bidding and a control without Smart+, with consistent ad-group settings and creatives. See the Playful Rewards case study.
This is evidence of a specific improvement within TikTok. It is not evidence that TikTok installs cost 32% less than Meta or Google installs. The page does not provide absolute CPI, sample sizes, a retained-user comparison, or the reward-adjusted contribution those users generated.
For an app that offers rewards, the commercial question comes after installation: do acquired users complete legitimate qualifying activity and continue producing value after reward costs? A low install price can help, but it cannot compensate for expensive incentives, invalid activity, or users who disappear before the business earns a return.
A second rewards-related example reaches further down the funnel. ATLAS:EARTH’s TikTok case study reports 44% Day 7 ROAS and a 47% reduction in iOS cost per purchase within the first two weeks of launch. The page also says TikTok became its number-one channel, without publishing a matched channel-by-channel comparison. See the ATLAS:EARTH case study.
Read that 44% correctly: it is a reported Day 7 ROAS level, not a 44% uplift and not proof of payback. Later revenue and the business’s costs would determine whether the cohort ultimately became attractive. It is evidence that downstream outcomes can be measured, not a margin guarantee.
Fintech and utility apps: look for meaningful activation
Snoop offers a more useful example than install volume alone. The UK personal-finance app optimized toward a first successful bank-account connection. TikTok reports that, after Snoop moved from standard manual campaigns to Smart+, CPI fell 40% while CPA for that key in-app event fell 62%. See the Snoop case study.
The deeper event improved more than the install metric in the reported comparison. That makes this a relevant hypothesis for fintech advertisers: acquisition value may come from finding users who complete a meaningful setup step. The public page does not disclose absolute CPA, cohort sizes, a retention result, or a simultaneous Meta/Google control. A bank connection is also not the same as a profitable customer.
Finanzguru, a German personal-finance utility app, provides a related value signal. Its TikTok case study describes iOS targeting in Germany and reports a 34% increase in customer lifetime value compared with previous campaign setups. It also acknowledges that earlier lower-funnel performance was not strong or consistent enough to justify further scaling. See the Finanzguru case study.
That caveat matters as much as the uplift. The page does not disclose the LTV calculation, observation horizon, absolute values, or whether the figure is realized or modeled. This finance utility example cannot stand in for every productivity, storage, or subscription app. For those businesses, define the useful action and retention evidence that fit the product before calling an acquisition inexpensive.
All four examples are selected, TikTok-published success stories. They describe different apps, markets, operating systems, events, and campaign changes. Their percentages should not be pooled into an average, used as a promised uplift, or treated as independent proof that TikTok beats competing platforms.
Underpriced and under-credited are different questions
An ad can introduce an app before another channel receives the eventual conversion credit. But changing the attribution model changes reported contribution; it does not itself create new customers.
Singular’s 2026 analysis places both TikTok and Meta across its three multi-touch metrics. It also reports up to 50% higher measured ROAS for Meta under multi-touch attribution than under last-touch reporting. Measurement-related undervaluation is therefore not an argument unique to TikTok. Read the attribution findings.
Use attribution analysis to ask better questions about the customer journey. Use an appropriately designed holdout or lift study, where feasible, to investigate how much additional business a channel causes. Do not add platform-reported conversions together and assume the total represents distinct new customers.
How to compare the next dollar of spend
The useful question is whether an additional allocation to TikTok can deliver qualified growth at a better cost than the next allocation to Meta or Google. Historical account-wide averages can hide differences in audience, campaign maturity, and the amount already spent.
Start with a defined market, operating system, acquisition period, and outcome. Separate prospecting from returning-user activity. Use the same reporting currency and a consistent treatment of attribution windows, revenue, refunds, incentives, and fees. Let every cohort reach the same observation age before comparing it.
Keep a compact scorecard for each channel: media spend; installs and CPI; qualified activations and cost per activation; retained qualified users at an agreed age; and realized net contribution or an explicitly labeled value estimate. Include creative and management costs when deciding whether the overall program is economical.
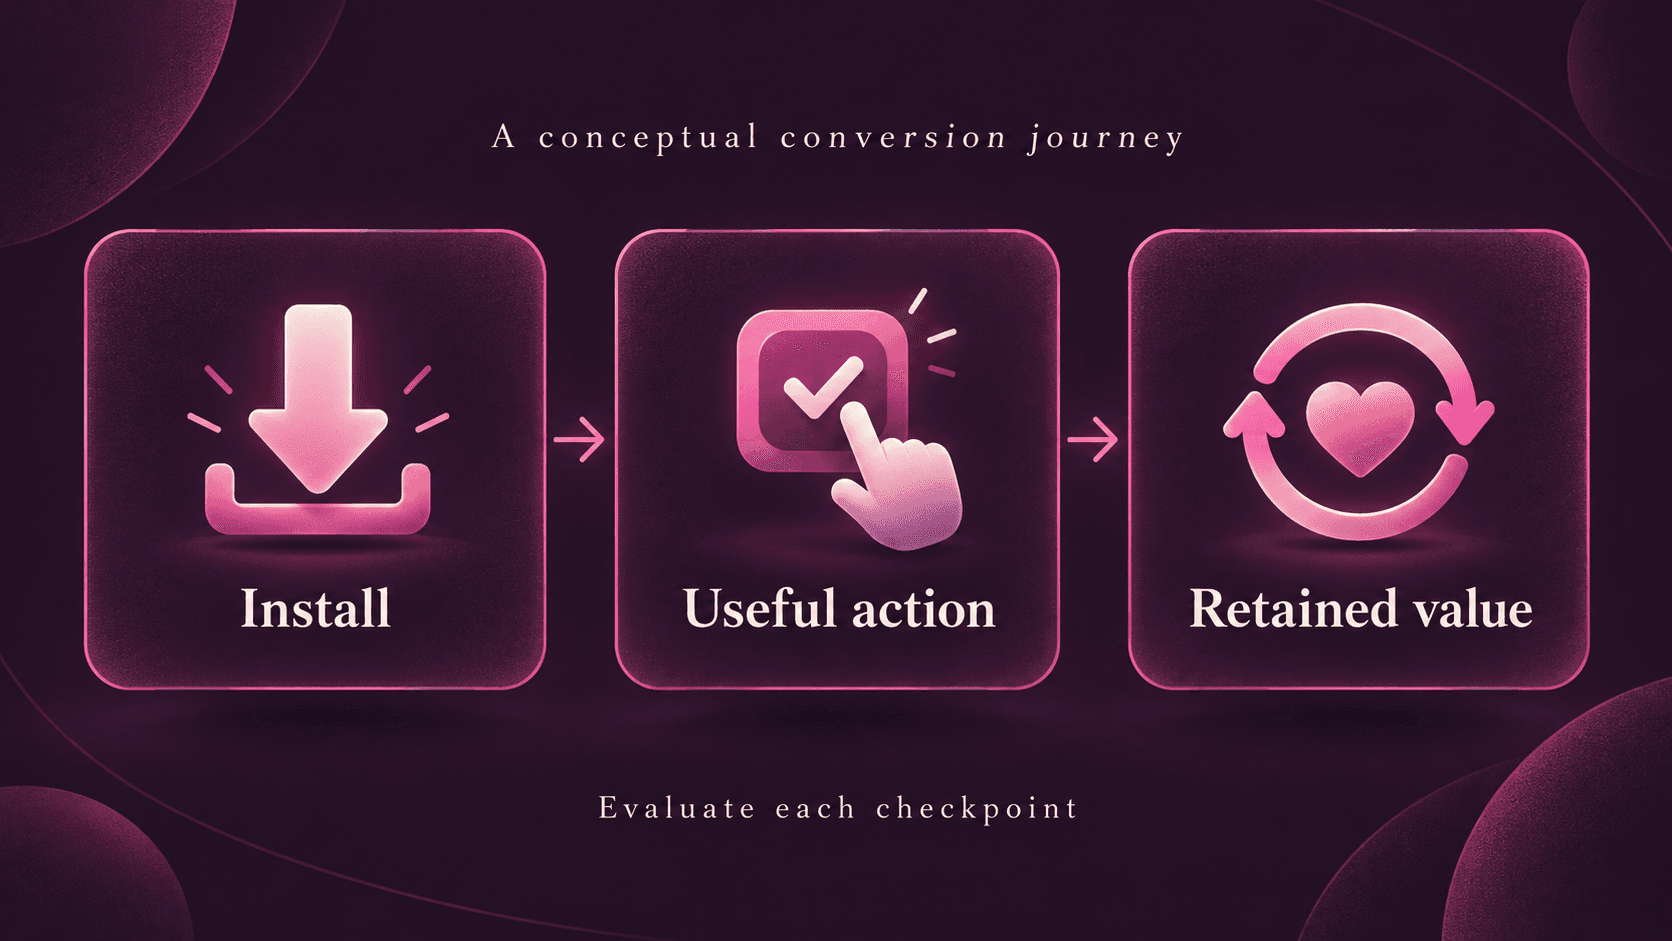
For example, suppose two fictional campaigns each spend $10,000. Campaign A buys 5,000 installs at $2 CPI and activates 10%, producing 500 qualified users at $20 each. Campaign B buys 2,500 installs at $4 CPI and activates 30%, producing 750 qualified users at about $13.33 each. The cheaper install loses on acquisition of qualified users. These are illustrative numbers, not TikTok, Meta, or Google benchmarks.
Give each channel a fair creative test. Keep the underlying proposition and approved offer comparable, while adapting execution to the placement. A short product demonstration can test whether viewers understand the benefit; a creator explanation can test whether a difficult setup step feels worthwhile. Neither requires an unsupported earnings promise or a misleading preview of the app.
Agree the spending ceiling, minimum evidence, and review date with the client before launch. The chosen outcome must have time to mature. If the budget cannot generate enough qualified events to distinguish ordinary variation from a meaningful difference, report the result as inconclusive rather than promoting a channel winner.
When TikTok deserves more budget
The case for increasing TikTok spend becomes stronger when its qualified-user cost remains competitive as spend rises, downstream value survives a consistent cohort comparison, and the acquisition is commercially useful after relevant costs. It becomes weaker when cheap installs fail to activate, retention falls, or the apparent advantage disappears after measurement is aligned.
That is where TikTok can still be underpriced in 2026: for a specific advertiser, in a specific market, relative to the useful value it can deliver and the alternatives available at the margin. Rewards, fintech, and utility advertisers have credible reasons to test that proposition. They should ask their growth partner to prove it with the right comparison.
Source and benchmark notes
Sources checked 16 October 2026. The cross-channel evidence uses AppsFlyer’s 2025 index and Singular’s 2026 analysis; these are different reports, not one combined dataset. The case-study pages do not provide enough dated, matched cohort detail to establish a 2026 three-platform CPI or profitability benchmark. All case-study results above are attributed to their publishers. Recommendations and the fictional arithmetic example are BerryGood Media’s analysis. No private campaign results are used.